Velosurance Review: Coverage, Cost, Claims & What to Know
If you own an expensive bicycle or e-bike, standard homeowners or renters insurance may not provide the type of protection you expect. That’s one reason specialist bicycle insurance has become an option for cyclists who want dedicated coverage.
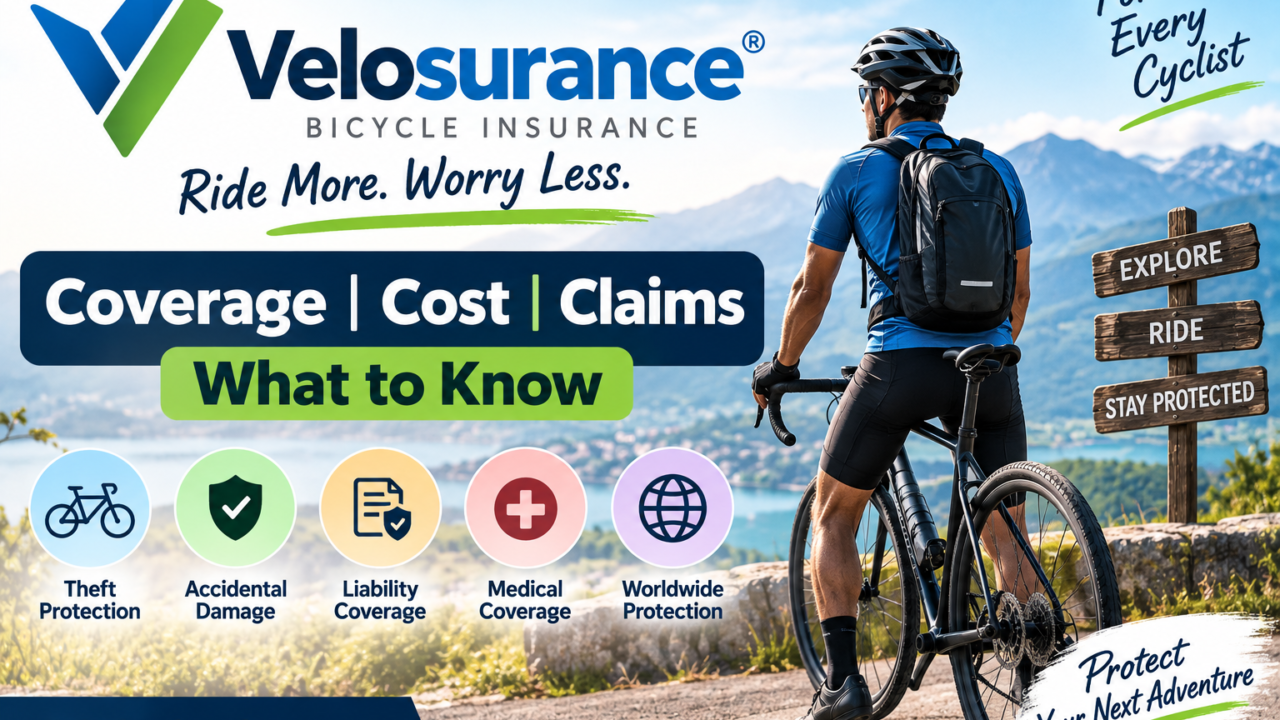
Velosurance is a U.S.-based bicycle insurance specialist that offers insurance designed specifically for cyclists. Its policies can cover bicycles against theft and accidental damage, with additional options for areas such as liability, medical payments and uninsured motorists. The policy is underwritten and issued by Markel American Insurance Company.
But is Velosurance suitable for your bike?
That depends on the value of your bicycle, where you ride, how you use it and the type of protection you need.
This guide explains what Velosurance is, what it covers, how much it costs, how deductibles work, how claims are handled, e-bike coverage and the important details to check before buying a policy.
Important: Insurance coverage, pricing, limits and availability can vary by location and policy. This article is for informational purposes. Always review the actual policy documents before purchasing insurance.
What Is Velosurance?
Velosurance is a specialist bicycle insurance provider focused on coverage for cyclists.
The company says it was founded by cyclists and developed a multi-risk bicycle insurance product covering different types of riders. Its current policy can cover theft and accidental damage, including certain losses while a bicycle is being transported.
Unlike a general homeowners policy, a specialist bicycle policy is designed specifically around risks associated with owning and riding a bicycle.
That can matter if you own a high-value road bike, mountain bike, racing bicycle, commuter bike or e-bike.
How Does Velosurance Work?
The basic process is similar to purchasing other types of insurance.
You provide information about your bicycle, choose the value you want to insure, select a deductible and choose any additional coverage available to you.
Velosurance says the quote process takes less than five minutes and allows customers to adjust the deductible and coverage options while obtaining a quote.
Before purchasing, you should look at the actual policy terms rather than relying only on information presented on a quote page.
One useful feature is that Velosurance currently allows prospective customers to review a policy specimen before purchasing. The company says the specimen contains the applicable definitions, coverages, exclusions and conditions.
What Does Velosurance Cover?
The exact coverage depends on the policy and options selected.
According to Velosurance’s current information, its bicycle policy provides protection for risks including:
- Theft
- Accidental damage
- Crash damage
- Certain transit losses
- Optional liability
- Optional medical payments
- Optional uninsured motorist coverage
- Other policy-specific benefits
The standard bicycle protection is described by Velosurance as an all-risk policy, meaning covered physical losses are generally subject to the policy’s exclusions and conditions rather than being limited to a short list of named accidents.
That doesn’t mean every possible loss is automatically covered.
The exclusions and conditions in the policy remain important.
Does Velosurance Cover Bicycle Theft?
Yes, theft is one of the risks Velosurance says its bicycle policy covers.
Its current FAQ states that an insured bicycle can be covered against theft at home and away from home when the bicycle is securely locked to an immovable object, subject to the policy terms.
This is an important distinction.
If your bicycle is stolen, the circumstances surrounding the theft can matter. Don’t assume that simply owning a policy means every theft scenario will automatically qualify for payment.
Read the policy’s security and locking requirements before relying on the coverage.
Does Velosurance Cover Accidental Damage?
Velosurance says its bicycle policy covers accidental damage, including damage resulting from crashes.
This can be particularly relevant for expensive bicycles because a crash can damage components that are costly to repair or replace.
For a covered repair, the policy can reimburse eligible repair costs subject to the applicable deductible and policy terms. Velosurance states that covered repair claims can include parts and labor.
Does Velosurance Cover E-Bikes?
Yes.
Velosurance’s current information says it covers Class 1, Class 2 and Class 3 e-bikes and e-trikes. It describes the coverage as all-risk, replacement-cost protection, with theft, crash damage and other covered losses subject to the policy terms.
The company currently describes the three e-bike classes as:
- Class 1: Pedal-assisted motor, with assistance up to 20 mph.
- Class 2: Motor assistance through a throttle, up to 20 mph.
- Class 3: Pedal-assisted speed up to 28 mph, with a speedometer.
Local laws can affect how e-bikes are classified and used, so the classification used by your manufacturer and applicable jurisdiction is important.
Velosurance also says its e-bike coverage uses replacement-cost protection without depreciation based on the age of the e-bike.
How Much Does Velosurance Cost?
As of September 2026, Velosurance says its bicycle insurance policies start at $100 per year. However, that is a starting figure, not a universal price.
The actual premium depends on factors including:
- Bicycle type
- Frame material
- Insured value
- Location
- How you ride
- Selected coverage
- Deductible
- Other underwriting factors
Velosurance says insured value and location have a significant influence on the premium.
For e-bikes, Velosurance currently gives a broader U.S. market estimate of approximately $100–$300 per year for standalone e-bike insurance, although individual premiums can fall outside that range.
The most useful way to determine your actual price is to obtain a quote for your particular bicycle rather than relying on an online average.
What Is the Velosurance Deductible?
A deductible is the amount you are responsible for paying toward a covered loss.
For example, if your covered bicycle damage totals $2,000 and your deductible is $200, the insurer’s stated example would result in a $1,800 payment after the deductible.
Velosurance says the deductible applies to each covered loss.
Generally, choosing a higher deductible can reduce the premium, while a lower deductible can increase the premium.
The right amount depends on how much you would be comfortable paying out of pocket after a loss.
How Is a Velosurance Bicycle Valued?
One of the important features to understand is how the insured value is established.
Velosurance describes its bicycle policy as a stated-value replacement-cost policy.
The company says customers set the insured value based on what they actually spent on the bicycle, including eligible accessories and component upgrades, with documentation such as receipts used to support the value.
Velosurance also states that covered total losses are paid up to the insured value, less the applicable deductible, without depreciation based on the bicycle’s age.
This makes it particularly important to choose an accurate insured value.
If you’ve upgraded your bicycle after buying the policy, check whether the insured value should be updated.
Does Velosurance Cover Bikes While Traveling?
Velosurance says its standard coverage is effective throughout the USA and Canada for theft and accidental damage, including certain loss or damage while the bicycle is transported by road or air.
The company also offers an optional worldwide coverage feature. Its current FAQ says worldwide coverage costs 10% of the annual premium when needed and can be added for a single trip and removed afterward through the customer portal.
Because geographic coverage can depend on the policy and applicable terms, check the exact policy before taking an expensive bicycle overseas.
Does Velosurance Offer Liability Coverage?
Yes, liability is available as an optional coverage.
Liability protection can be relevant when a cyclist causes bodily injury or property damage to another person.
Velosurance specifically discusses liability as an option for riders who share roads with cars or ride around pedestrians and groups.
Don’t assume liability coverage is automatically included simply because you have bicycle insurance.
Check your declarations page and policy wording to confirm which options you’ve purchased.
Does Velosurance Offer Medical Coverage?
Velosurance offers optional medical-related coverage.
Its current information describes medical coverage as potentially useful for expenses that remain after a rider’s existing health insurance pays its share.
The amount and terms of any medical coverage should be checked against your own health insurance because deductibles, copays and other benefits can differ.
What Is Uninsured Motorist Coverage?
Cyclists sometimes share roads with vehicles, which creates a particular risk if a driver causes an accident and doesn’t have adequate insurance.
Velosurance offers optional uninsured motorist coverage. Its current information says this can provide protection for certain medical and related expenses when an at-fault driver is uninsured or cannot be identified after a hit-and-run.
Whether you need this coverage depends partly on your existing insurance and the risks associated with how and where you ride.
Does Velosurance Cover Racing?
Competitive cycling can create insurance questions that don’t always apply to casual riding.
Velosurance currently lists Competitive Use as an optional coverage. Its comparison information says this can apply to racing and related competitive activities, subject to the policy terms.
If you participate in organized races, don’t assume ordinary recreational coverage is sufficient.
Check that competitive use is actually included in your policy.
Does Velosurance Cover Rental Bikes?
There is a specific rental-bike benefit in certain circumstances.
Velosurance currently says that when a covered loss makes your insured bicycle unavailable while you are more than 50 miles from home during an organized cycling event, trip or race, the policy can reimburse reasonable expenses for a temporary replacement bicycle, up to the applicable benefit limit.
The company’s current FAQ states a limit of $250 per occurrence for this benefit and says there is no deductible applied to it.
This is not the same as general coverage for any rental bicycle used for casual recreation.
How Do Velosurance Claims Work?
Velosurance says claims can be started online.
The company recommends having relevant information ready, including:
- Policy details
- Date of the loss
- Description of what happened
- Photographs of damage
- Police report where applicable
- Repair estimate
After the claim is submitted, a claims professional reviews the information and guides the customer through repair or replacement.
For a theft claim, keeping purchase receipts and other ownership documentation can be especially important because the insured value may need to be supported.
Who Underwrites Velosurance?
This is an important detail that is sometimes missed when researching an insurance brand.
Velosurance’s current FAQ states that its bicycle policy is underwritten and issued by Markel American Insurance Company, based in Glen Allen, Virginia.
Velosurance handles the service side of the relationship, including quotes, policy changes and claims assistance, according to the company.
Understanding the difference between the insurance brand and the underwriting insurer can help you know whose policy contract you’re actually purchasing.
Velosurance vs. Homeowners Insurance
One of the most important questions for bicycle owners is whether specialist insurance is necessary when they already have homeowners or renters insurance.
The answer depends on the coverage already available under your existing policy.
A homeowners policy may provide some protection for bicycles, but it can have different limits, deductibles, depreciation rules and exclusions.
Velosurance specifically highlights differences involving theft away from home, accidental bicycle damage, e-bikes and liability-related coverage.
Before buying another policy, compare your existing insurance with the specialist policy line by line.
Look at:
| Feature | Check With Existing Policy | Check With Velosurance |
|---|---|---|
| Theft | Coverage, limits and deductible | Theft conditions |
| Crash damage | Whether covered | Physical-damage coverage |
| Bicycle value | Actual/replacement/depreciated value | Declared insured value |
| E-bike | Whether included | Eligible e-bike classes |
| Liability | Existing personal liability | Optional bicycle liability |
| Medical expenses | Existing health coverage | Optional medical coverage |
| Deductible | Policy-specific | Selected bicycle deductible |
| Travel | Geographic limits | USA/Canada and optional worldwide coverage |
The point isn’t that one policy is automatically better for every cyclist. It’s that the coverage should be compared based on your actual needs.
Velosurance Discounts
Velosurance currently lists several ways customers may reduce the bicycle portion of their premium.
According to its current FAQ:
- Insuring two bikes can provide a 10% bicycle-coverage discount.
- Insuring three or more bikes can provide a 15% bicycle-coverage discount.
- Eligible USA Cycling, USA Triathlon and IMBA members can receive another 10% discount.
- A higher deductible can reduce the premium.
Discount availability and eligibility can change, so verify the terms when obtaining a quote.
What Should You Check Before Buying Velosurance?
Don’t make a decision based solely on the monthly or annual premium.
Before purchasing, check:
1. The Policy Document
Velosurance currently allows customers to review the policy specimen before buying. Read it.
2. Your Bicycle’s Insured Value
Make sure the declared value accurately reflects what you’re trying to protect.
3. Your Deductible
Choose an amount you could realistically pay after a covered loss.
4. Theft Conditions
Pay close attention to locking and security requirements.
5. Optional Coverage
Determine whether you need liability, medical, uninsured motorist, worldwide or competitive-use coverage.
6. Geographic Coverage
Check where your policy applies if you travel with your bicycle.
7. E-Bike Classification
If you own an e-bike, verify its class and eligibility.
8. Claims Requirements
Keep receipts, photographs and ownership records in a safe place.
Who Might Consider Velosurance?
A specialist bicycle policy may be worth investigating if you:
- Own a high-value bicycle
- Have an expensive e-bike
- Regularly travel with your bicycle
- Participate in cycling events
- Want dedicated theft protection
- Want protection for accidental bicycle damage
- Need optional cycling-related liability coverage
- Want coverage specifically designed around bicycle ownership
That doesn’t mean every cyclist needs specialist insurance.
Someone with a low-value bicycle and substantial existing coverage may have different insurance needs from someone who owns a $5,000 road bike or high-end e-bike.
What Are the Potential Limitations?
Before buying any insurance policy, consider the limitations as well as the benefits.
For Velosurance, some important points to investigate include:
- It is a specialist bicycle insurance product rather than general worldwide insurance.
- Coverage depends on the policy and optional coverages selected.
- Deductibles apply to covered physical losses.
- Theft coverage has specific conditions.
- International coverage requires attention to geographic terms.
- Pricing varies by bicycle, location and coverage.
- Policy terms can change, and availability can vary by jurisdiction.
The company’s policy specimen is the best place to verify the contractual details that apply to your policy.
Frequently Asked Questions
What is Velosurance?
Velosurance is a specialist bicycle insurance provider offering insurance for bicycles and e-bikes. Its policy is underwritten and issued by Markel American Insurance Company.
How much does Velosurance cost?
As of September 2026, Velosurance says its policies start at $100 per year. Your actual premium depends on factors such as bicycle value, location, bike type, deductible and selected coverage.
Does Velosurance cover e-bikes?
Yes. Velosurance currently says it covers Class 1, Class 2 and Class 3 e-bikes and e-trikes, subject to its policy terms.
Does Velosurance cover stolen bikes?
Yes, theft is covered subject to the policy conditions. Velosurance states that theft coverage can apply at home and away from home when its security requirements are met.
Does Velosurance cover crash damage?
Velosurance says its bicycle policy covers accidental damage, including crash damage, subject to the policy’s terms, exclusions and deductible.
Does Velosurance cover racing?
Competitive-use coverage is available as an optional coverage according to Velosurance’s current comparison information. Riders involved in racing should verify that the appropriate coverage is included in their policy.
Does Velosurance cover bikes outside the USA?
Velosurance currently says standard coverage is effective in the USA and Canada for theft and accidental damage. It also offers optional worldwide coverage, subject to the applicable terms.
What deductible does Velosurance use?
The deductible is selected when setting up the policy and applies to each covered physical loss. Velosurance says choosing a higher deductible can reduce the premium.
How do I file a Velosurance claim?
Velosurance says claims can be started online. You may need policy information, details of the loss, photographs, a police report for theft and a repair estimate where applicable.
Who underwrites Velosurance?
Velosurance’s bicycle policy is underwritten and issued by Markel American Insurance Company.
Final Thoughts
Velosurance is a specialist bicycle insurance option designed around risks that cyclists may face, including theft and accidental damage. It also offers optional protections such as liability, medical payments, uninsured motorist and worldwide coverage.
Its current pricing starts at $100 per year, but the actual premium depends on your bicycle, location, deductible and selected coverage.
For e-bike owners, Velosurance currently states that Class 1, Class 2 and Class 3 e-bikes are eligible, subject to the policy terms.
Whether it makes sense for you depends on the value of your bicycle, how you use it and what protection you already have through homeowners, renters, health or other insurance.
Before purchasing, compare the coverage—not just the price—and read the actual policy document, including its exclusions, conditions and deductible.
Thalla Lokesh
Thalla Lokesh is a Digital Marketing Strategist and SEO Specialist with over 12 years of experience in helping businesses grow their online presence. Since beginning his career in 2013, he has successfully worked across industries including healthcare, education, technology, and e-commerce. He specializes in search engine optimization (SEO), content marketing, keyword strategy, and link building, with a strong focus on delivering measurable results. Lokesh has helped brands achieve top rankings on Google through data-driven strategies, high-quality content, and ethical SEO practices aligned with search engine guidelines. As the founder of Honey Web Solutions , a Tirupati-based digital marketing company, he actively works with clients to improve organic traffic, lead generation, and online visibility. He also contributes expert insights on digital marketing trends, AI SEO, and content strategies through blogs and industry platforms.